• Level 5, Evandale Place, 142 Bundall Road, Bundall, QLD, Australia

Author: admin

What happens if your builder collapses mid-build?

When a major builder gets into financial trouble, subcontractors can quickly find themselves exposed for work they have already completed, materials they have supplied and invoices that remain unpaid. That risk has been highlighted by the voluntary administration of Sydney-based Bathla Group. The major residential developer entered voluntary administration in August 2026 with roughly 2,000 homes under construction. Administrators have since identified about $3.4 billion in known consolidated creditor claims. Voluntary administration does not automatically mean a business will be liquidated. However, it can immediately change what creditors are able to do to recover money they are owed. It’s a NSW story, but the problem is just as relevant to Gold Coast subcontractors and suppliers. What is an unpaid invoice actually worth once the builder above you becomes insolvent? Can you take back materials you haven’t been paid for? And what should you do when the first warning signs appear? What happens to your unpaid invoices? Once a company enters voluntary administration, the position changes quickly. Under section 440D of the Corporations Act 2001 (Cth), legal proceedings against the company generally can’t be started or continued without the administrator’s written consent or leave of the court. That can leave a subcontractor who has completed $100,000 of work with a valid $100,000 debt, but no guarantee of recovering $100,000. One Bathla contractor reportedly found itself in exactly this position, telling the ABC that it was owed close to $400,000 for work, labour and materials and had been preparing legal proceedings shortly before Bathla entered administration. The problem is particularly acute for unsecured creditors. If you don’t have effective security or another payment protection available, you may need to lodge and substantiate your claim in the external administration. What you ultimately recover will depend on what happens to the company, the assets available and, if a deed of company arrangement is proposed, the terms of that deed. This is why speaking to debt recovery lawyers or an insolvency lawyer at the first signs of trouble, before a builder formally collapses, can be important. A civil litigation lawyer can also advise on your options if an unpaid construction debt has developed into a dispute. Unfinished work creates another risk The unpaid invoice is only part of the problem. What do you do with the work you haven’t finished? Simply walking off site can be risky because your right to suspend work will depend on the contract and applicable legislation. But continuing to work for a builder that has stopped paying can be equally dangerous because it increases your financial exposure. Under section 98 of Queensland’s Building Industry Fairness (Security of Payment) Act 2017 (Qld) (BIF Act), a claimant is provided a statutory right to suspend construction work or the supply of related goods and services in certain circumstances. If the amount owed under a payment claim hasn’t been paid in full by the due date, a claimant can give written notice of their intention to suspend under the BIF Act. At least two business days must then pass before work is suspended. The process needs to be followed correctly, so getting advice before you stop work can help avoid creating another contractual dispute. Why a retention of title clause may not protect you Suppliers sometimes assume a retention of title clause means materials remain theirs until the builder pays for them. But the Personal Property Securities regime makes the position more complicated. A retention of title arrangement generally creates a security interest in the goods supplied. The Australian government’s Personal Property Securities Register (PPSR) warns that if you don’t register that interest, you will be an unsecured creditor if your customer becomes insolvent. In other words, putting a retention of title clause in your terms and conditions is not enough by itself to protect your priority. Timing is also key, and it depends on who your customer is and what they do with the goods. Your “customer” here is whoever you contracted with and delivered the goods to, which might be the builder directly or a subcontractor further down the chain if you’re supplying them rather than the head contractor. Retention of title interests will commonly be purchase money security interests (PMSIs), and specific registration timeframes apply depending on what your customer does with the goods once delivered: Construction materials create an extra complication. The PPSR applies to personal property, but generally not to land, buildings or fixtures. That means the position can change once materials are fixed to the building, so a retention of title clause and PPSR registration may not give you a right to simply remove installed materials. Missing the relevant deadline can mean losing PMSI super-priority, even though a later registration may still be effective as an ordinary security interest. Separate timing rules also apply when the customer is a company, so registering security interests early is important. There is another important limitation for tradies: the PPSR protects security interests in personal property. An unpaid invoice for labour or services does not, on its own, give you a security interest that can be protected simply by making a PPSR registration. There must be a valid security interest in personal property. A commercial lawyer on the Gold Coast can review terms of trade and security arrangements before problems arise rather than trying to fix them after a customer becomes insolvent. Queensland subcontractors have other payment protections Queensland subcontractors potentially have several avenues available under the BIF Act. One is adjudication. A subcontractor who makes an eligible payment claim and isn’t paid in full may be able to apply for adjudication, but strict deadlines apply. Another option may be a subcontractors’ charge. This can effectively ‘leapfrog’ the contractor that owes you money and freeze money still payable to that contractor by someone higher in the contractual chain. However, that protection has a crucial limitation: it only works if money is still owing further up the chain. Strict time limits also apply, and you generally can’t use adjudication and a subcontractors’
When a property scam hits, who’s legally on the hook?

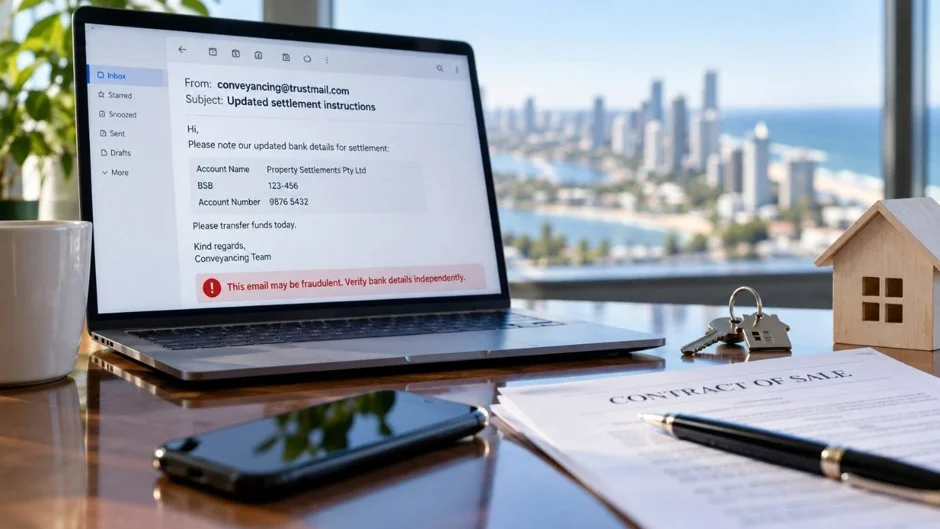
Property settlement scams are becoming harder to spot as criminals use increasingly sophisticated technology to impersonate trusted people involved in a transaction. PEXA’s latest Settlement Scams Index found 92% of respondents were aware of at least one type of property scam, yet confidence in being able to detect one fell to 41%, down from 51% a year earlier. With large sums changing hands during Gold Coast property transactions, falling for a convincing scam can be financially devastating. It also raises a complicated question. If the money reaches a scammer instead of the intended recipient, who ultimately bears the loss? How do property settlement scams work? According to the PEXA report, business email compromise remains the biggest threat during settlement. A criminal may access an email account or imitate a real estate agent, conveyancing lawyer or another property professional involved in the transaction, then send altered bank details at the moment funds are expected. PEXA also identifies AI-enabled voice cloning as an emerging threat, with 62% of respondents concerned about its use, potentially making impersonation attempts even more convincing. The research, conducted in July 2026 among 1,028 Australians who had recently bought or intended to buy property, tested detection skills directly. The National Anti-Scam Centre reported combined losses of $166.8 million from payment redirection scams across Australia in 2025, up from $152.6 million in 2024, second only to investment scams. Who bears the loss when settlement funds are misdirected? There is no rule that automatically makes the buyer, seller, Gold Coast property lawyer, conveyancer or bank responsible. The answer may depend on the contractual payment obligation, where the fraudulent instructions originated, and whether another party owed and breached a relevant duty. A Queensland decision illustrates the starting point. In Factory Direct Fencing Pty Ltd v Kong AH International Company Ltd [2013] QDC 239, a fraudster interfered with email communications between a buyer and a supplier, and the buyer transferred payment to the fraudster. The District Court declined to impose the duty of care alleged against the supplier. The buyer had also been alerted to a problem when its bank advised that the beneficiary details did not match the account number, but proceeded without confirming the changed details with the supplier by telephone or another non-email method. That was a commercial supply matter rather than a residential settlement, but it shows why transferring money does not necessarily mean a payment obligation has been met. What if the hacked account belonged to the other party? Mobius Group Pty Ltd v Inoteq Pty Ltd [2024] WADC 114 shows the same problem reaching an Australian court more recently. A third party accessed the genuine email account of contractor Mobius and sent changed bank details to Inoteq, which owed Mobius money. Inoteq attempted to verify the change by telephone, but its employee could not hear Mobius’s response because of the poor connection. Rather than making another call, Inoteq then sought confirmation by email through the very account that had been compromised, and made the payment. The District Court of Western Australia found in favour of Mobius and ordered Inoteq to pay $191,859.16 plus interest. In reaching its decision, the court considered that Inoteq was in the better position to protect itself from the fraud, including by making another telephone call to verify the changed account details. A Western Australian decision does not bind a Queensland court, but it provides another Australian example of a payer remaining liable after transferring money in reliance on fraudulent payment instructions. Could a conveyancing lawyer be liable? A different question arises where the conduct of a solicitor contributed to the loss. Queensland’s electronic conveyancing operates under the Electronic Conveyancing National Law (Queensland), and solicitors also owe professional and fiduciary duties to clients. Whether conveyancing solicitors on the Gold Coast could be liable would depend on their role, the instructions received, what happened when payment details were provided or changed and the particular legal duties that applied. Neither of the cases above involved a solicitor, and in each the loss stayed with the party that made the payment. A claim against a conveyancing lawyer would therefore turn on something more than the fact that a scam occurred during a transaction they were handling. Will a bank refund money lost in a property scam? A bank is not automatically required to reimburse a customer who authorised a payment to a scammer. However, whether a bank bears some responsibility can depend on the circumstances, including the warning signs available to it and the steps it took before and after the payment. Banks have rolled out Confirmation of Payee under the Scam-Safe Accord, which checks whether the account name entered matches the details held by the recipient bank. AFCA’s jurisdiction over scam complaints involving receiving banks expanded on 12 March 2026, meaning consumers and eligible small businesses may now be able to complain about both the bank sending the funds and the bank that received them. Complaints generally need to be raised with the relevant bank first before going to AFCA. Most obligations under Australia’s Scams Prevention Framework commence on 31 March 2027. Designated organisations have already been required to be AFCA members since 1 September 2026, while AFCA’s broader SPF complaints jurisdiction will commence from 31 March 2027. How can Gold Coast property buyers reduce the risk? PEXA found 84% of respondents said they would verify new payment instructions with a real, known person, face to face or by telephone. That verification needs to be independent. Obtain trust account details from your conveyancing lawyer at the outset using a number you sourced yourself, treat any change to payment instructions as suspect, and take Confirmation of Payee warnings seriously. Who ends up bearing the loss? Liability after a property settlement scam is rarely a single clean answer. The Australian cases discussed above show that the steps taken by the paying party to verify changed bank details can be important, which means transferring funds to a criminal may not discharge the original payment obligation. Questions

Insolvency lawyer guide: What to do when your business is in financial distress

Financial distress does not necessarily mean a business is insolvent. However, when cash-flow tightens, debts mount or creditors lose patience, delaying action can narrow the options that remain. Those pressures are real. Alares Credit Risk Insights[1]  reported that Australian insolvencies in August 2026 exceeded the corresponding level in 2025, while winding-up applications reached a new monthly high. In addition, more than 37,000 businesses were subject to Australian Taxation Office (ATO) tax debt reporting. Gold Coast company directors and business owners under financial pressure should understand the warning signs, their legal obligations and the options available before the position deteriorates further. Speaking with an insolvency lawyer early can also help clarify the legal implications of those options. What does it mean when a business is in financial distress Warning signs can include: The critical question is whether the company has crossed into insolvency. Under section 95Aof the Corporations Act 2001 (Cth), a company is solvent if it can pay all its debts as andwhen they become due and payable. The test therefore focuses on the company’s ability topay its debts on time, rather than simply whether its assets exceed its liabilities. What should you do when your business is in financialdistress? 1. Review your financial position The Australian Securities and Investments Commission (ASIC) recommends acting straightaway when a business is facing financial trouble. Bring your financial records up to date and review debts, cash-flow and money owed to thebusiness. This can help establish whether the business faces a temporary cash-flowproblem or deeper concerns about its ability to pay debts when they fall due.Business lawyers can provide legal advice where those financial concerns also raisequestions about directors’ duties, creditor action or insolvency. 2. Understand your duties as a director ASIC says directors must comply with their legal obligations when a company is in financialtrouble, including preventing insolvent trading. Under section 588G of the Corporations Act,directors have a duty to prevent a company from incurring debts where it is insolvent, orwould become insolvent by incurring them, in circumstances where there are reasonablegrounds for suspecting insolvency. A liquidator may pursue a director personally for compensation for loss or damage resultingfrom insolvent trading. An insolvency lawyer can advise a director on their legal positionwhen insolvency is suspected. 3. Don’t ignore tax debt The ATO can disclose eligible business tax debts to credit reporting bureaus where, amongother requirements, at least $100,000 is overdue by more than 90 days and the business isnot effectively engaging with the ATO. A notice of intent generally gives the business 28days to act. Directors may also face personal exposure through director penalty notices for unpaid PAYGwithholding, GST and super guarantee charge. A Gold Coast business lawyer can adviselocal directors on the legal implications of tax debt and director penalty notices. What happens if a creditor serves a statutory demand? If debts remain unresolved, creditor enforcement can escalate quickly. One of the more serious steps a company may face is a statutory demand. A creditor owed at least $4,000 can serve a statutory demand under section 459E of the Corporations Act. A company generally has 21 days to comply or apply to have the demand set aside. For a set-aside application, the application and supporting affidavit must be filed, and copies served on the creditor, within that 21-day period. Failure to comply can create a rebuttable presumption of insolvency supporting a winding-up application. The 21-day period for making a valid set-aside application is strict, making immediate advice from an insolvency lawyer important. Can a financially distressed business keep trading? Financial distress does not automatically mean a business must close. Depending on the circumstances, there may be options that allow the company to continue trading while directors work to improve its financial position. Safe harbour can provide directors with protection from civil liability for insolvent trading for debts incurred directly or indirectly in connection with a qualifying course of action that is reasonably likely to lead to a better outcome for the company, provided the statutory requirements are met. Businesses may also be able to negotiate payment arrangements with creditors before formal insolvency proceedings become necessary. Business lawyers can assist with the legal aspects of creditor negotiations where appropriate. If creditor negotiations and a viable turnaround strategy are not enough, directors may need to consider formal restructuring or insolvency processes. What formal restructuring and insolvency options are available Eligible companies may consider small business restructuring. This allows directors toremain in control while working with a registered restructuring practitioner on a plan fordealing with creditors. Total liabilities must not exceed $1 million, among other eligibilityrequirements. Other options include voluntary administration, where an administrator takes control of thecompany and assesses its financial position and future. Liquidation involves a liquidatortaking control of the company, realising its assets and distributing available funds tocreditors. The appropriate option depends on the company’s assets, liabilities, cash-flow andprospects of recovery. An insolvency lawyer can help directors understand the legalimplications of the available pathways.For Gold Coast businesses operating in the building and construction industry, the choice ofinsolvency pathway can also have licensing consequences. What does insolvency mean for a Gold Coast building licence? Construction generates 22.2% of Gold Coast output compared with 14.1% acrossQueensland, according to economy.id, making the consequences of insolvency particularlyrelevant to local building businesses. CHART 1: Construction as a share of economic output Region Construction share of output Gold Coast 22.2% Queensland 14.1% Source: economy.id, 2023/24. Under Queensland law, a director involved in certain insolvency events can become anexcluded individual and be unable to hold a QBCC licence for three years. Two separaterelevant insolvency events may result in permanent exclusion. Small business restructuring does not itself involve appointing an administrator or liquidator,although a licensed company must still satisfy the QBCC’s minimum financial requirements.A Gold Coast business lawyer can advise on the legal considerations surrounding financialdistress alongside the specific QBCC requirements that may apply. Where can Gold Coast businesses get help? Eligible Queensland small businesses experiencing or at risk of financial hardship canaccess free financial counselling, including debt support

Wills and estates lawyer: planning your legacy on the Gold Coast

Estate planning involves more than deciding who inherits what when you die. It can also mean protecting family and business interests, planning for incapacity and ensuring different assets and structures are dealt with appropriately. A will is an important part of this process, but it may not cover every asset or circumstance. This is where a wills and estates lawyer can help. QBM Lawyers works with individuals, families and business owners across the Gold Coast to develop a coordinated estate plan – one that reflects your wishes and is in line with Queensland law. 1. Create a valid will A will is the foundation of your estate plan. It identifies your beneficiaries, appoints an executor to administer your estate, and sets out how your assets should be distributed. If you die without a will (known as dying intestate), your estate will be distributed according to Queensland’s intestacy provisions under the Succession Act 1981 (Qld). This statutory formula may not reflect your wishes, particularly if you have a blended family, are in a de facto relationship, or own a business with more complex asset structures. It’s worth reviewing your will after significant life events. Marriage generally revokes an existing will unless an exception applies, while divorce can revoke provisions relating to a former spouse. Having children, losing a beneficiary or executor, or acquiring or disposing of significant assets may also mean your will no longer reflects your current circumstances.. For couples, mutual wills may be worth considering. Mutual wills involve a binding agreement about how certain property will ultimately be distributed, often including an agreement not to change the agreed arrangements after the first person dies. They can be useful in circumstances such as blended families, where both parties want greater certainty about how assets will eventually pass to their children. However, mutual wills can significantly limit flexibility and do not prevent family provision claims, so it is important to discuss whether they are appropriate with an estate lawyer. 2. Consider a testamentary trust and statement of wishes A testamentary trust is created under your will and comes into effect after your death. Rather than passing directly to a beneficiary, assets can be held and managed within the trust. This may be useful where beneficiaries are minor children, face financial or relationship risks, or where greater control over the management and distribution of an inheritance is desirable. A statement of wishes is a separate, usually non-binding document that sits alongside your will. It helps explain your intentions and gives additional guidance to an executor or trustee on matters such as how you would like a testamentary trust to be managed or your wishes regarding the care of minor children. 3. Plan for assets outside your will A complete estate plan needs to look beyond the assets dealt with directly by your will. Some assets, such as certain jointly owned property and assets held in a trust, may not form part of your estate. Others, including business interests, may form part of your estate but still require separate succession planning. Superannuation is also subject to its own rules about who can receive a death benefit. Superannuation Recent Super Consumers Australia research found that just 13% of people surveyed said they had made a binding death benefit nomination. The organisation estimates that at least 15.5 million Australians may not have one in place, meaning their super fund trustee may retain discretion over who receives their benefit if no other binding arrangement applies. Your super death benefit does not automatically form part of your estate or get distributed according to your will. Without a binding death benefit nomination, the trustee of your super fund generally has discretion to decide who receives your benefit, depending on the fund and its rules. A binding nomination directs the trustee to pay your death benefit to an eligible dependant or your legal personal representative, provided the nomination is valid and in effect. Some binding nominations lapse after a specified period, while others may be non-lapsing. Trusts Assets held by a family or discretionary trust are generally owned by the trustee rather than by you personally, so they cannot be distributed through your will. Succession will instead depend on the trust deed, including how it deals with the appointor or principal – the person who typically has the power to appoint or remove the trustee. Business interests For business owners, a buy and sell arrangement can set out what happens to your interest in the business if you die or become incapacitated. These arrangements, often supported by insurance, can provide certainty for surviving owners and your family, while helping to avoid disputes over valuation or ownership. Because estate planning often intersects with tax, superannuation, trust structures and business succession, an experienced estate lawyer can work alongside your accountant or financial adviser to help ensure your plan is properly coordinated. 4. Planning for incapacity, not just death Estate planning isn’t only about what happens after you die. It also covers who can make decisions for you if you lose the capacity to make them yourself, whether due to illness, injury or age. An enduring power of attorney, made under Queensland’s Powers of Attorney Act 1998, allows you to appoint someone you trust to make financial and/or personal matters, including health decisions, on your behalf. For personal and health matters, your attorney can only act when you do not have capacity to make the relevant decision yourself. For financial matters, you can choose when their authority begins, including immediately, from a specified time or when you lose capacity. Unlike a general power of attorney, an enduring power of attorney can continue to operate if you lose capacity. An advance health directive allows you to give directions about future health care, including certain end-of-life and life-sustaining treatment decisions, if you’re unable to make or communicate those decisions yourself. How to reduce the risk of an estate dispute Even a carefully prepared will can be challenged. Under Queensland law, a family provision